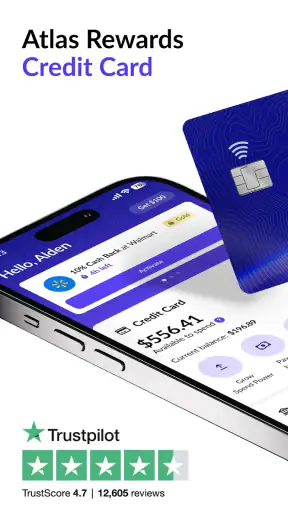
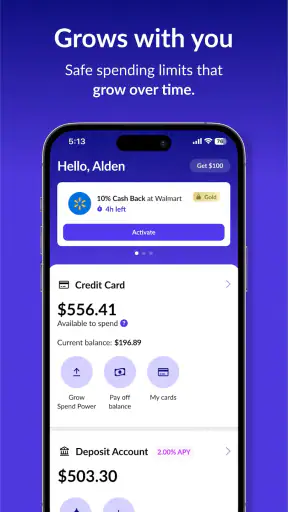
I approached Atlas - Rewards Credit Card as a practical finance app rather than as another budgeting dashboard. Its central appeal is simple: it brings cash-back rewards and credit-building into the same experience. That combination can be useful for someone who wants to make everyday spending more purposeful, but it also requires a little more attention than a normal rewards app. In my experience, the value comes from using it consistently and understanding how each purchase fits into a wider credit routine.
Developed by Exto Inc., Atlas is free to use and is rated for Everyone. It has built a strong audience in the finance category, with a 4.6 average from roughly 174 thousand ratings and more than a million installs. Those figures do not make it automatically right for every user, but they do suggest that the app has become a familiar option for people looking at rewards and credit-building together.
The current Android release is version 6.0.10, and it supports devices running Android 7.1 or later. I would describe it as most useful for someone who wants one focused place to think about card activity, rather than for a person searching for a complete replacement for a bank account, an investment platform, or a detailed expense-management suite.
Why the cash-back and credit-building combination matters
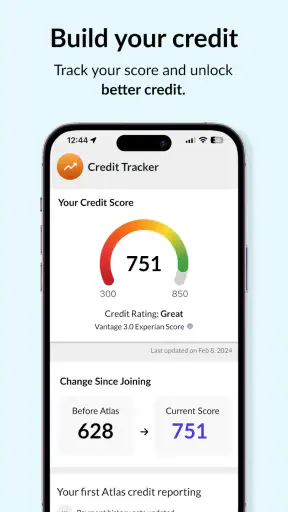
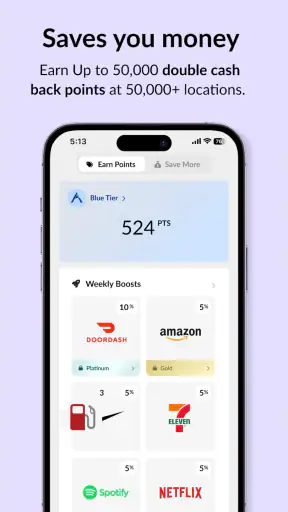
The capability that stands out is the way Atlas connects two goals that are often treated separately. Cash back gives an immediate reason to use a card for ordinary purchases, while credit building is a longer-term objective that depends on responsible account habits. Putting both ideas together changes how I look at the app: the reward is the visible benefit, but the credit-building side is the part that may matter more over time.
That distinction is important. A reward can feel satisfying after a purchase, yet a credit-building product should not be judged only by how attractive the reward sounds. The more useful question is whether the app helps you develop a repeatable routine: use the account thoughtfully, keep track of activity, and avoid treating available credit as extra income. Atlas makes the most sense when those habits are the priority.
I also like that the concept is understandable without requiring a complicated financial setup. Someone who is new to credit can see a clear reason to engage with the app, while a more experienced user may appreciate having rewards attached to spending they already planned to do. Still, the two goals can pull in different directions. Chasing cash back can encourage unnecessary purchases, whereas building credit rewards patience and control. The app cannot remove that tension; the user has to manage it.
For that reason, I would not install Atlas simply because the word “rewards” sounds appealing. I would install it if I wanted a structured way to make responsible credit activity feel worthwhile. That is a narrower promise, but it is also a more realistic one.
What the app is really useful for
I see three practical uses. First, it can give a newcomer a reason to start paying attention to credit rather than ignoring it. Second, it can make planned spending feel more organized by connecting purchases with a cash-back objective. Third, it can serve as a dedicated card experience for someone who does not want to mix credit-building activity with every other financial account.
The strongest use is the first one. People often know that credit matters but do not know how to turn that knowledge into a daily habit. Atlas gives the habit a visible purpose. Instead of thinking only about an abstract future benefit, the user has a present-day reason to review purchases and stay engaged.
The app is less compelling for someone who already has a mature credit strategy and a rewards card that clearly outperforms it for their particular spending. In that situation, Atlas may add another account to monitor without adding enough value. It is also not the right fit for anyone who tends to spend more when rewards are available. No cash-back feature can compensate for purchases that would not have happened otherwise.
Using Atlas in an ordinary week
In practice, I would use Atlas around planned purchases rather than letting it dictate what I buy. Imagine a week with groceries, a train ticket, and a household item already on the shopping list. The sensible workflow is to check the account before spending, use it only where the purchase is affordable, and then review the activity afterward. The reward becomes a small benefit attached to an existing need, not a reason to create a new one.
That post-purchase review is where the app’s credit-building purpose becomes more meaningful. I would not stop at checking whether cash back appeared. I would also look at the account as part of my broader monthly plan: what has already been spent, what remains available in my budget, and whether the next payment can be handled comfortably. This extra step is easy to skip, but it separates useful credit practice from casual card use.
A practical tip is to create a simple personal rule before using the account. For example, I might reserve Atlas for recurring essentials or purchases already covered by money in my checking account. That rule reduces the temptation to spend merely to collect rewards. It also makes the account easier to evaluate because I can see whether it supports my normal routine instead of distorting it.
Another useful habit is to review transactions in batches. Rather than opening the app after every small purchase, I would check it at a consistent time, such as after a grocery trip or at the end of the week. This keeps the process manageable while still making unfamiliar activity easier to notice. The trade-off is that a batch review requires discipline; the app can show activity, but it cannot make a distracted user examine it carefully.
I would also keep Atlas separate in my mental budget. Even if the app makes rewards visible, I would not subtract expected cash back from the cost of a purchase. Treating a future reward as an immediate discount can make spending appear cheaper than it really is. The safer approach is to regard rewards as a later benefit and judge every purchase at its full cost.
Questions I would settle before relying on it
A new user will naturally want to know whether Atlas is completely free, whether it can replace a bank, and whether using it guarantees a stronger credit profile. The first point is clearer: the app itself is free. That does not mean every financial decision connected with a credit product should be treated as costless, so I would still read the account terms carefully before committing to regular use.
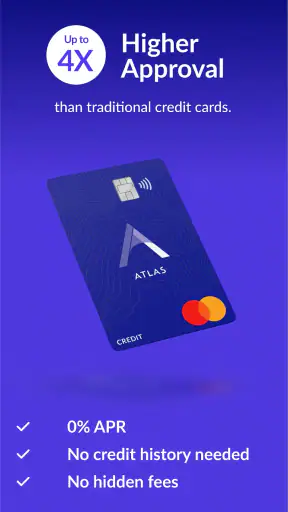
It is also important to separate the app from the wider financial relationship around it. Atlas is a finance app built around the Atlas card experience; I would not treat it as a general-purpose checking account or a full budgeting replacement. If your main need is bill categorization, savings goals, or a complete picture of several bank accounts, a dedicated budgeting tool may be better suited.
Credit building is another area where expectations need to be realistic. Using the app responsibly may fit into a credit-building plan, but simply installing it or making purchases does not turn credit into an automatic result. Your behavior matters: spending within your means, monitoring the account, and following the relevant account obligations are more important than the presence of a rewards balance.
I would also ask myself whether I need instant rewards or long-term structure. If I mainly want the highest possible return on a particular category of spending, a traditional rewards card with a clearly defined earning system may be easier to compare. Atlas is more interesting when the credit-building objective is central and the cash-back element helps maintain engagement.
The best scenario for this app
The best scenario is a person who is beginning to establish credit, has predictable income or available funds for planned purchases, and wants a reason to check their account regularly. For that user, Atlas can turn a vague financial goal into a repeatable routine. The cash-back element gives the routine some immediate feedback, while the credit-building purpose encourages a longer view.
Consider someone furnishing a first apartment. They may have ordinary purchases to make, but they do not want to open a card simply to chase promotions. Using Atlas for selected, budgeted expenses could make those transactions part of a more deliberate credit habit. The important word is “selected.” I would not put every expense on the account automatically, especially if doing so makes the monthly budget harder to follow.
This scenario also shows why the app may appeal to younger users without being limited to them. A person who has never managed a credit account may prefer a focused experience with a clear purpose. Someone rebuilding financial confidence after avoiding credit could also find the combination approachable. In both cases, the app works best as a tool for consistency, not as a shortcut.
Families may need to think more carefully. If one person manages the account but another person makes purchases, the rewards can make shared spending harder to interpret unless everyone follows the same budget rules. I would use Atlas for a clearly assigned purpose rather than treating it as an informal household pool.
For freelancers and people with irregular income, the decision is more complicated. Cash back may still be useful, but unpredictable income makes it especially important to avoid spending ahead of available funds. I would only recommend the app in that situation if the user already has a reliable way to reserve money for card obligations.
The trade-offs behind the convenience
The main limitation is behavioral, not cosmetic. Rewards can make ordinary spending feel productive even when it is unnecessary. Atlas therefore rewards attention twice: attention to what you buy and attention to how the account fits into your finances. Someone looking for a completely passive benefit may become frustrated because the useful outcome depends on their choices.
There is also a comparison problem. Traditional credit cards can offer more familiar reward structures, broader product ecosystems, or features that suit established users. A banking app may provide a more complete view of cash flow. A credit-monitoring service may focus more directly on reports and alerts. Atlas occupies a middle ground, and that is both its identity and its limitation.
I would not choose it as my only financial app if I needed detailed spending analysis. The store summary focuses on earning cash back and building credit, not on replacing every financial tool. That focus is welcome, but it means users should understand what they are getting: a targeted credit-and-rewards experience rather than an all-in-one money manager.
Another trade-off is that combining rewards with credit-building can make comparison less straightforward. A card with a larger headline reward is not automatically better for a new credit user, just as a credit-focused product is not automatically better for someone who spends heavily in categories served by another card. I would compare the whole routine, including convenience, account management, spending control, and the user’s ability to follow through.
Device compatibility is fairly broad because the app supports Android 7.1 and newer, but anyone using an older phone should check compatibility before planning around it. The release history also matters in a practical way: keeping the app updated is sensible for a finance product, both for access to the current experience and for avoiding problems caused by an outdated installation.
Small habits that improve the experience
My first tip is to decide what the app is for before the first purchase. “Build credit” is too broad as a daily instruction, while “use it only for planned essentials and review activity weekly” is actionable. A defined purpose makes it easier to tell whether Atlas is helping or simply adding another place to spend.
My second tip is to track the cash-back balance separately from the money needed for payments. Rewards are psychologically easy to spend before they are actually useful. Keeping them mentally separate prevents the app’s most attractive feature from weakening the credit-building routine.
My third tip is to use the app as a prompt for financial review, not as proof that a purchase was wise. After checking a transaction, I would ask whether the purchase was planned, whether it fits the month’s budget, and whether I would have made it without the reward. That last question is especially revealing.
A fourth insight is that Atlas may be more valuable during a stable period than during a financial emergency. When money is tight, rewards can distract from the more important question of whether spending should happen at all. In that circumstance, a simple debit-based budget may be safer and easier to control.
Who should choose Atlas?
I would recommend Atlas to someone who wants a focused credit-building app with a cash-back reason to stay engaged. It is particularly suitable for a first credit account, a cautious return to credit use, or a person who prefers a simple, dedicated routine over a large collection of financial products.
I would be more hesitant for an experienced rewards optimizer. If you already compare earning categories, redemption values, and card benefits in detail, Atlas may not be the strongest primary choice. You may get more from a conventional rewards card or from a banking setup that gives you deeper control over spending and account management.
I would also tell anyone with a history of impulse spending to approach it slowly. The right test is not whether the app makes rewards visible; it is whether you can use the account without increasing your spending. If that test fails, the cash-back feature is working against the credit-building goal.
Exto Inc. has positioned Atlas in a useful space for people who do not want to choose between a reward-oriented experience and a credit-focused one. Its 4.6 average and audience of more than a million installs show broad interest, while the free entry point makes it easy to explore. But popularity and accessibility should not replace personal judgment.
My final view is that Atlas - Rewards Credit Card is best understood as a habit-building tool with a reward attached. I like the idea because it gives a practical reason to engage with credit, and I think it can be a good fit for planned spending and steady account review. I would skip it if I wanted a complete money-management platform, the most aggressive rewards strategy, or a product that requires almost no personal oversight. Used carefully, though, it offers a clear and approachable way to connect everyday purchases with a longer-term credit goal.


